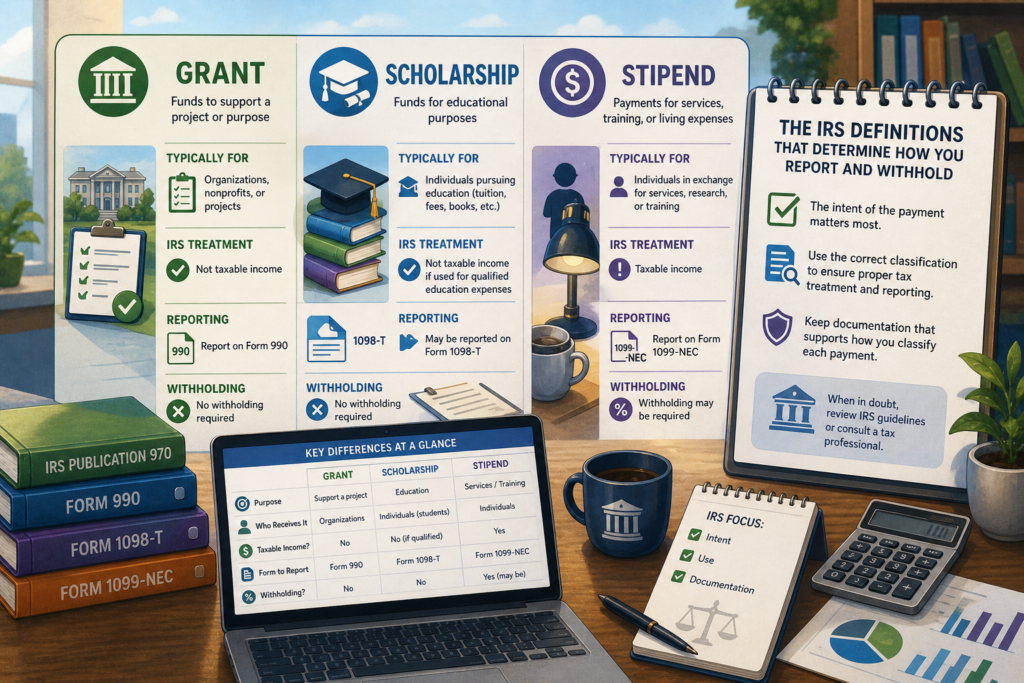
Grant vs. scholarship vs. stipend, the IRS treats each differently, and misclassifying them means wrong forms, missed withholding, and real audit exposure. Three payments, three labels, three potential compliance failures.
Most organizations already know the rules. The breakdown happens in the systems that tag, report, and withhold. The ones that stay compliant are those whose financial infrastructure enforces the right treatment before money moves.
TL;DR
- The IRS treats grants, scholarships, and stipends differently, wrong classification means wrong forms (1099-MISC, W-2, or 1042-S), missed withholding, and direct audit exposure
- Scholarships are only tax-free for qualified education expenses; stipends are almost always taxable and easily reclassified as wages if services are involved
- Nonresident alien recipients trigger mandatory withholding (14–30%) and Form 1042-S obligations most organizations aren’t operationally ready for
- The compliance failure is the systems and workflows that let misclassification happen upstream, before finance ever sees the payment
- Crowded enforces classification logic at the point of disbursement, so nonprofits and foundations stop correcting errors at year-end and start preventing them at the source
Grant vs. Scholarship vs. Stipend: How the IRS Defines Each
What Is a Grant (IRS Perspective)?
“Grant” isn’t a single IRS-defined category. Treatment depends on who receives it and what they must do.
- Individuals: Usually taxable unless an exclusion applies.
- Businesses: Almost always taxable; typically reported on Form 1099-MISC.
- Foundations: Under IRC §4945, grants to individuals must follow IRS-approved procedures or risk excise taxes.
Key question: Does the recipient have to perform services? If yes, it may be compensation.
What Is a Scholarship?
Scholarships have clearer rules under IRC §117. To be tax-free, both must apply:
- The recipient is a degree candidate
- Funds are used for qualified education expenses
Qualified (tax-free):
- Tuition and required fees
- Books, supplies, and required equipment
Not qualified (taxable):
- Room and board
- Travel
- Optional/personal expenses
Example: A $10,000 scholarship with $7,000 for tuition and $3,000 for housing → $7,000 tax-free, $3,000 taxable.
Taxable portions are reported by the recipient on Schedule 1 (Form 1040), Line 8r.
What Is a Stipend (and Why It’s Risky)?
“Stipend” is not an IRS-defined category.
- Generally taxable income
- No automatic exclusions, even for students
The bigger risk is reclassification:
- If tied to services (teaching, research, admin work), it may be treated as employee compensation
- This triggers payroll taxes, W-2 reporting, and withholding
Bottom line: “Stipend” is a label. Misuse often leads to compliance issues later.
The Tax Treatment Breakdown: What Changes in Practice
When Is Each Type Taxable?
Payment Type | Taxability Rule |
Grant | Generally taxable unless awarded under a specific exempt purpose; grants to businesses are nearly always taxable |
Scholarship | Tax-free only for qualified education expenses; amounts covering non-qualified expenses are taxable |
Stipend | Usually fully taxable; may be reclassified as wages if tied to services |
Who Reports the Income?
Recipients are responsible for reporting taxable amounts on their own returns.
- Scholarships (taxable portion): Reported on Schedule 1 (Form 1040), Line 8r if not on a W-2
- Stipends: Reported on Schedule 1 or via Form 1099
For organizations, reporting depends on classification:
- Form 1099-MISC: Grants or stipends to non-employees (≥ $600)
- Form W-2: Required if payments are compensation for services
- Form 1042-S: Payments to nonresident aliens
Why it matters: Misclassifying (e.g., issuing a 1099 instead of a W-2) can create payroll tax liabilities, penalties, and interest.
Withholding Rules That Change Everything
For U.S. citizens and residents:
- Generally, no withholding on scholarships
- Tax is paid when filing or via estimates
- If tied to services → W-2 + payroll withholding applies
For nonresident aliens:
- 14% withholding on taxable scholarships (F, J, M, Q visas)
- 30% withholding for others (unless reduced by treaty)
- Reported on Form 1042-S
Withholding can be reduced with:
- Form W-8BEN (treaty claims)
- Form 8233 (compensation/scholarship exemptions)
Default rule: Withhold at statutory rates until valid documentation is received.
The IRS Reclassification Trap: Where Most Organizations Fail
When a Scholarship or Grant Becomes Wages
The biggest risk is missing when a payment should be wages.
Trigger: If payment requires teaching, research, or any service, that portion is taxable compensation. It must be:
- Reported on Form W-2
- Subject to income and payroll tax withholding
Example: A graduate “fellowship” covers tuition + a stipend.
- Tuition → tax-free (if qualified under Section 117)
- Stipend tied to teaching → wages (W-2)
This isn’t a gray area, IRS guidance (e.g., Publication 970) is clear.
Why This Happens at Scale
The issue is structural.
- Program teams define payments early (offer letters, awards)
- Terms like “stipend” are used inconsistently
- Finance receives requests too late to reclassify cleanly
Fixing it at year-end doesn’t solve the problem:
- Missed payroll taxes still trigger penalties and interest
- Corrections don’t undo compliance gaps
- Auditors see it as a control failure
Misclassification starts upstream and gets expensive fast.
Calculating the Taxable Portion: Applied Examples
Example 1 — Scholarship Split
A student receives a $10,000 scholarship:
- $7,000 for tuition/required fees: tax-free
- $3,000 for housing: taxable
For a U.S. resident student, the school generally does not withhold, but the student reports the $3,000 on Schedule 1 (Form 1040), Line 8r.
Example 2 — Stipend Reclassification
A student receives a $5,000 “research stipend” but must work 15 hours per week in a lab.
Because the payment requires services, it should be treated as wages, meaning the organization should:
- Run it through payroll
- Withhold applicable taxes
- Report it on Form W-2
Issuing a 1099 instead creates compliance exposure.
Example 3 — Nonresident Alien Recipient
A J-1 scholar receives an $8,000 U.S.-source fellowship stipend for living expenses.
Because it is taxable, the institution must:
- Withhold 14% = $1,120
- Report it on Form 1042-S
- File annual Form 1042
- Provide Form 1042-S by March 15
Treaty relief may apply, but only if valid documentation is received before payment.
Why This Breaks in Multi-Program Organizations
IRS rules are clear in theory. In practice, multi-program nonprofits struggle to apply them consistently.
Different programs use the same labels (“stipend,” “grant”) to mean different things. Finance receives payment requests with inconsistent classifications and little documentation. Manual review doesn’t scale, so errors get fixed at year-end.
This is a workflow gap between knowing the rules and applying them in real time.
The Infrastructure Gap: Where Things Fail
Most teams understand the rules. The breakdown happens in execution:
- Classification: Program staff label payments based on intent, not IRS definitions.
- Disbursement: Payments go out without validating residency, service requirements, or withholding.
- Reporting: Inconsistent data turns year-end filings (1099, W-2, 1042-S) into a messy reconciliation.
More training won’t fix this. Systems need to enforce rules at the point of entry.
How Modern Financial Infrastructure Fixes It
Strong compliance comes from systems:
- Standardized classifications: Structured categories tied to IRS rules reduce ambiguity.
- Automated withholding: Correct rates apply based on recipient status.
- Reclassification guardrails: Service-based payments are flagged before disbursement.
- Centralized reporting: Clean data makes year-end filing straightforward.
Shift from fixing errors after the fact to preventing them altogether.
Turn Payment Classification Into Built-In Compliance Control
Most payment platforms help nonprofits move money. Crowded helps nonprofits control the compliance logic behind every payment before money moves.
For organizations managing grants, scholarships, and stipends across multiple programs, Crowded helps reduce misclassification risk by making each payment follow a structured workflow:
- Consistent payment categories across grants, scholarships, stipends, payroll, and vendor payments
- Early flags for service-based payments that may need payroll treatment instead of accounts payable
- Built-in support for nonresident alien withholding workflows, so tax status and reporting requirements are easier to manage
- Cleaner year-end reporting because payment data is captured correctly at the source
The value is simple: fewer manual reviews, fewer year-end surprises, and stronger audit readiness. With Crowded, classification becomes more than a label. It becomes a financial control that helps nonprofits protect compliance before payments go out.
Classification Is an Infrastructure Decision
The IRS rules are straightforward: qualified scholarships are tax-free, service-linked stipends are wages, and grants to nonresident aliens may require withholding and Form 1042-S.
The hard part is applying those rules across many programs, recipients, and transactions, especially when non-finance staff classify payments before compliance review.
Organizations that get this right stop treating classification as a judgment call. They make it a system property. Their financial infrastructure enforces rules, flags exceptions, and prevents misclassification before money moves.
That shift, from compliance as knowledge to compliance as infrastructure, is what keeps issues from surfacing only during an audit.
Frequently Asked Questions
What's the difference between a grant, scholarship, and stipend for IRS purposes?
A scholarship is tax-free only for degree candidates using funds on qualified expenses under IRC §117. A grant’s taxability depends on who receives it and whether services are required. A stipend has no formal IRS definition, it’s evaluated on substance, making it the riskiest label.
Can a single payment be partly taxable and partly tax-free?
Yes. A $10,000 scholarship covering tuition and housing isn’t fully tax-free, only the tuition portion qualifies. Crowded captures this split at entry, so taxable and non-taxable portions are recorded correctly before disbursement.
Does labeling a payment a "stipend" protect against reclassification?
No. If a payment requires teaching, research, or any service, the IRS treats it as wages, regardless of the label. W-2 reporting, payroll taxes, and withholding all apply.
What happens if we issue a 1099 instead of a W-2?
The organization owes unpaid payroll taxes, interest, and penalties, and flags a control weakness to auditors. Crowded flags service-based payments before disbursement so compensation never gets routed through accounts payable by mistake.
Do nonprofits have withholding obligations on scholarships?
Not for U.S. residents. For nonresident aliens, withholding is mandatory, 14% for F, J, M, Q visa holders; 30% for others, unless a valid treaty claim is on file before payment.
How does Crowded help multi-program organizations stay compliant?
Crowded enforces compliance logic at the payment level, structured IRS-aligned classifications, built-in nonresident alien withholding, and service-payment flags before disbursement. Year-end 1099, W-2, and 1042-S reporting reflects clean data from the source.