


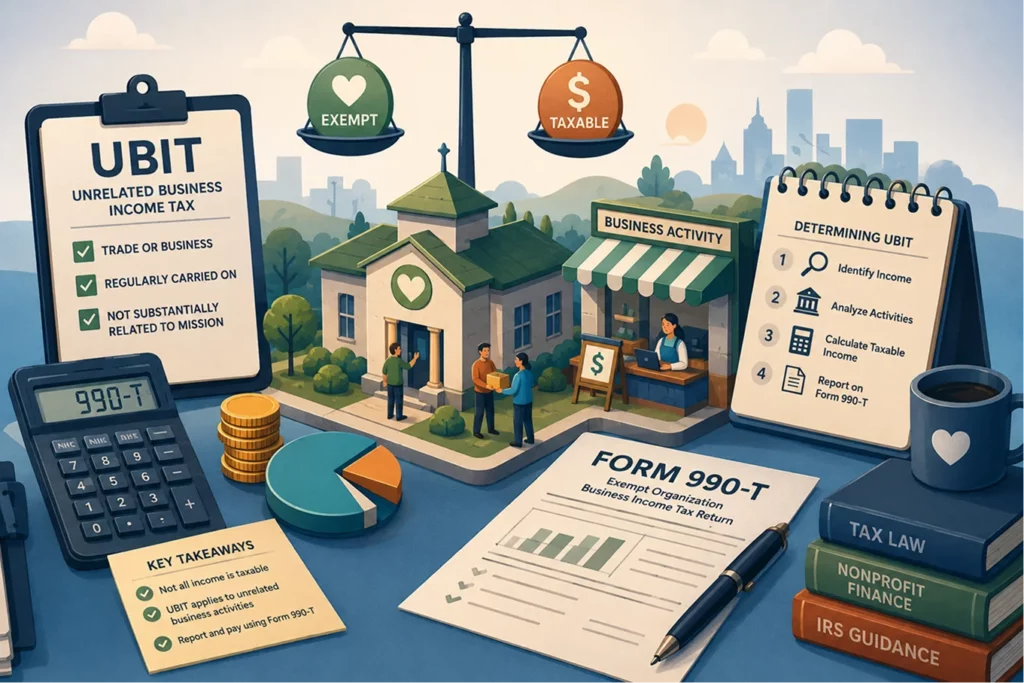
What is UBIT for nonprofits? UBIT, or unrelated business income tax, is the tax a nonprofit may owe when it earns income from activities that are regularly carried on, run like a business, and not substantially related to its exempt mission.
A nonprofit can be tax-exempt and still have nonprofit taxable income. UBIT does not tax donations, grants, or mission-related program revenue. It targets commercial income that falls outside the organization’s exempt purpose.
This article provides general information. Nonprofits should consult a qualified tax professional for organization-specific guidance.
TL;DR
- UBIT applies when a nonprofit earns income from regular, commercial, unrelated business activities.
- Common UBIT triggers include advertising revenue, unrelated merchandise sales, debt-financed rental income, paid vendor placements, and commercial chapter activities.
- Form 990-T may be required once gross unrelated business income reaches $1,000, even if the activity produces little or no profit.
- Chapter-based nonprofits face higher UBIT risk because revenue often lives across local accounts, spreadsheets, sponsorships, and event workflows.
- Crowded* helps nonprofit finance teams improve revenue visibility, track chapter activity, and organize financial records before UBIT questions become year-end problems.
What Is UBIT for Nonprofits?
UBIT exists to prevent tax-exempt organizations from gaining an unfair advantage over taxable businesses when they engage in commercial activities.
For a UBIT nonprofit analysis, the IRS generally looks at three questions:
- Is the activity a trade or business?
- Is it regularly carried on?
- Is it not substantially related to the nonprofit’s exempt purpose?
If the answer is yes to all three, the income may be unrelated business taxable income.
What Does UBIT Apply To?
UBIT applies to income from business-like activities that are outside the nonprofit’s charitable, educational, religious, scientific, or other exempt purpose.
Common UBIT examples include:
- Selling merchandise unrelated to the mission through an online store.
- Running a paid job board for employers.
- Selling commercial advertising in a newsletter.
- Renting debt-financed property to outside parties.
- Operating a café open to the public.
- Licensing mailing lists to vendors.
- Hosting unrelated paid trainings for nonmembers.
- Selling sponsorship packages that provide advertising benefits.
The key issue is not whether the income helps fund the mission. The question is whether the activity itself furthers the mission.
Decision Matrix: Is the Revenue Likely Subject to UBIT?
Revenue activity | Likely UBIT? | Why |
Donations | No | Contributions are not business income. |
Membership dues | Usually no | Often tied to exempt activity. |
Mission-related event fees | Usually no | Supports exempt programming. |
Paid ads in a newsletter | Often yes | May trigger nonprofit advertising income tax. |
Qualified sponsorship recognition | Usually no | Recognition is different from advertising. |
Rental income from real property | Often no | Passive rent is generally excluded. |
Debt-financed rental property | Possibly yes | Can trigger nonprofit rental income UBIT. |
Online store selling unrelated goods | Often yes | Commercial activity outside the mission. |
What Is Included in Unrelated Business Taxable Income?
Unrelated business taxable income, or UBTI, generally includes gross income from an unrelated trade or business, minus directly connected deductions. Included revenue may come from advertising, unrelated sales, unrelated service fees, certain royalties, partnership income, debt-financed income, or commercial activities conducted by chapters.
Excluded revenue may include donations, qualified sponsorship payments, dividends, interest, certain royalties, and many forms of passive rental income. Exceptions matter, so documentation is critical.
Is Advertising Revenue Taxable for Nonprofits?
Sometimes, yes. Nonprofit advertising income tax can apply when a nonprofit sells promotional space that includes calls to action, pricing, product claims, endorsements, or links designed to drive sales.
For example, a simple sponsor acknowledgment may say: “Thank you to ABC Bank for supporting our annual conference.” An advertisement may say: “Open an account with ABC Bank today and get $300.” That type of promotional benefit may expose you to UBIT.
Is Rental Income Subject to UBIT?
Rental income is often excluded from UBIT when it comes from real property and remains passive. But nonprofit rental income UBIT can arise when:
- The property is debt-financed.
- The rental includes substantial services.
- The agreement includes personal property rent.
- The rental activity resembles an active business.
Example: A nonprofit renting an unused office to another organization may avoid UBIT. But a nonprofit running a full-service event venue with catering, staffing, equipment, and frequent commercial bookings may need closer review.
How Is UBTI Calculated?
A basic UBTI calculation looks like this:
Gross unrelated business income
minus directly connected expenses
minus allowable deductions
equals unrelated business taxable income
Example:
A nonprofit earns $20,000 from unrelated advertising. It spends $6,000 on design, sales, and publishing costs directly tied to that advertising.
$20,000 gross unrelated income
minus $6,000 directly connected expenses
equals $14,000 UBTI before other allowable adjustments.
What Expenses Can Be Deducted Against UBTI?
Expenses must be directly connected to the unrelated business activity.
Deductible expenses may include:
- Staff time is tied to the activity.
- Payment processing fees.
- Advertising sales costs.
- Printing or publishing costs.
- Software used for the unrelated activity.
- Allocated overhead supported by records.
- Contractor costs.
The nonprofit should maintain clear records showing how each expense relates to income. Weak allocation records can create filing problems later.
What Activities Trigger UBIT?
Activities that may trigger UBIT include regularly selling unrelated goods, operating unrelated paid services, selling advertising, running commercial events, renting debt-financed property, or receiving unrelated income through partnerships. The word “regularly” matters. A one-time fundraiser may be treated differently from a year-round e-commerce store.
How Much Unrelated Business Activity Is Too Much?
There is no single safe percentage that applies to every nonprofit. UBIT itself does not automatically threaten tax exemption. However, if unrelated commercial activity becomes substantial compared with exempt activity, the organization may create an exempt status risk.
Finance leaders should monitor:
- Total unrelated income.
- Frequency of unrelated activity.
- Staff time devoted to commercial operations.
- Whether chapters are generating unrelated revenue.
- Whether the activity distracts from the exempt purpose.
When Is Form 990-T Required?
Form 990-T is generally required when a tax-exempt organization has $1,000 or more in gross income from unrelated business activities. This is based on gross unrelated business income. A nonprofit may need to file even if expenses reduce the taxable amount. Form 990-T is used to report unrelated business income and calculate unrelated business income tax liability.
Can UBIT Jeopardize Tax-Exempt Status?
Yes, but usually only when unrelated business activity becomes more than incidental. A nonprofit can pay UBIT and keep its exemption. The larger risk appears when the organization begins to look more like a commercial business than a mission-driven nonprofit. Strong governance, clean books, board oversight, and revenue classification help reduce that risk.
Why Chapter-Based Networks Face More UBIT Risk
Chapter-based nonprofits face a harder tracking problem. A national organization may have dozens or hundreds of chapters collecting dues, selling ads, hosting events, renting space, running stores, or accepting sponsorships. Some activities may be mission-related. Others may create unrelated business taxable income.
The challenge is visibility. If chapter revenue sits in disconnected bank accounts or spreadsheets, finance teams may miss UBIT exposure until year-end.
Common chapter risks include:
- Local newsletters sell ads.
- Chapter websites are selling vendor placements.
- Unrelated event revenue.
- Rental income from chapter-owned property.
- Merchandise stores.
- Sponsorship packages with advertising language.
How Crowded Helps Nonprofits Track UBIT Risk
Crowded helps nonprofit finance teams improve revenue visibility across chapters, accounts, payments, and restricted funds. For UBIT compliance, that visibility matters. Finance leaders need to know where revenue came from, which chapter collected it, what activity produced it, and whether it may need review before the Form 990-T season.
Crowded can help teams:
- Centralize chapter-level financial activity.
- Track revenue sources more clearly.
- Separate dues, donations, sponsorships, reimbursements, and program income.
- Improve oversight across distributed accounts.
- Preserve transaction records for finance and tax review.
- Spot unusual revenue patterns earlier.
Crowded provides nonprofit teams with a cleaner financial infrastructure, making it easier to identify, document, and escalate UBIT questions.
UBIT Compliance Starts With Revenue Visibility
UBIT is manageable when nonprofits understand their revenue. The practical goal is to classify income correctly, document expenses, monitor commercial activity, and file Form 990-T when required.
For chapter-based networks, this starts with better visibility into local financial activity. When revenue is scattered, UBIT risk hides in plain sight. When revenue is organized, finance teams can ask better questions earlier.
A strong UBIT process should help your nonprofit:
- Identify unrelated business income before year-end.
- Separate mission-related and commercial revenue.
- Support accurate UBTI calculation.
- Prepare for Form 990-T filing when needed.
- Protect exempt status through better oversight.
- Give chapters clearer financial guardrails.
UBIT compliance is a revenue visibility discipline.
* Crowded Technologies Inc is a financial technology company and is not a bank. Banking services provided by i3 Bank; Member FDIC. The Crowded Technologies Inc. Visa® Debit Card is issued by i3 Bank pursuant to a license from Visa U.S.A. Inc. and may be used everywhere Visa debit cards are accepted.
There are no fees associated with account opening, but transaction fees may apply; please refer to the Crowded Business Deposit Account Agreement for more details on account transaction fees.
Frequently Asked Questions
Does UBIT mean a nonprofit did something wrong?
No. UBIT simply means a nonprofit earned income from an activity that may be taxable. The key is tracking, reporting, and filing correctly.
Can corporate sponsorships trigger UBIT?
Why is UBIT harder for chapter-based nonprofits?
Chapters often collect revenue separately, making it harder for national teams to see advertising, rentals, sponsorships, or unrelated sales activity.
How can Crowded help with UBIT visibility?
Can separate accounts help with UBIT tracking?
What is the biggest UBIT mistake nonprofits make?
Waiting until tax season to classify revenue. UBIT compliance is easier when income is categorized throughout the year.



