Sub Accounts
Separate accounts for chapters, one view for headquarters
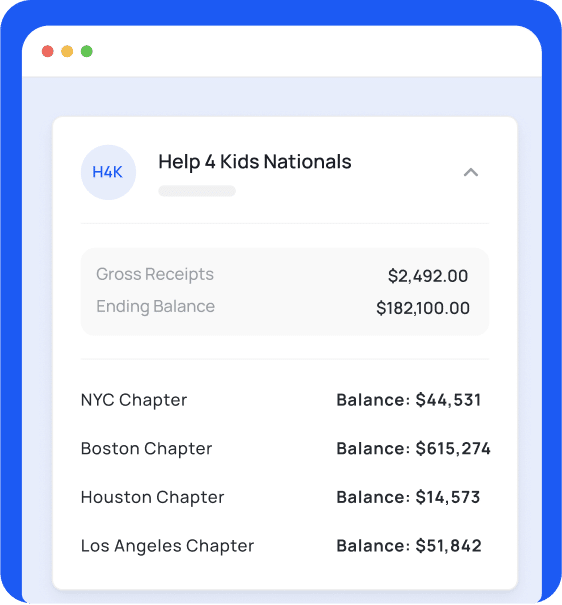
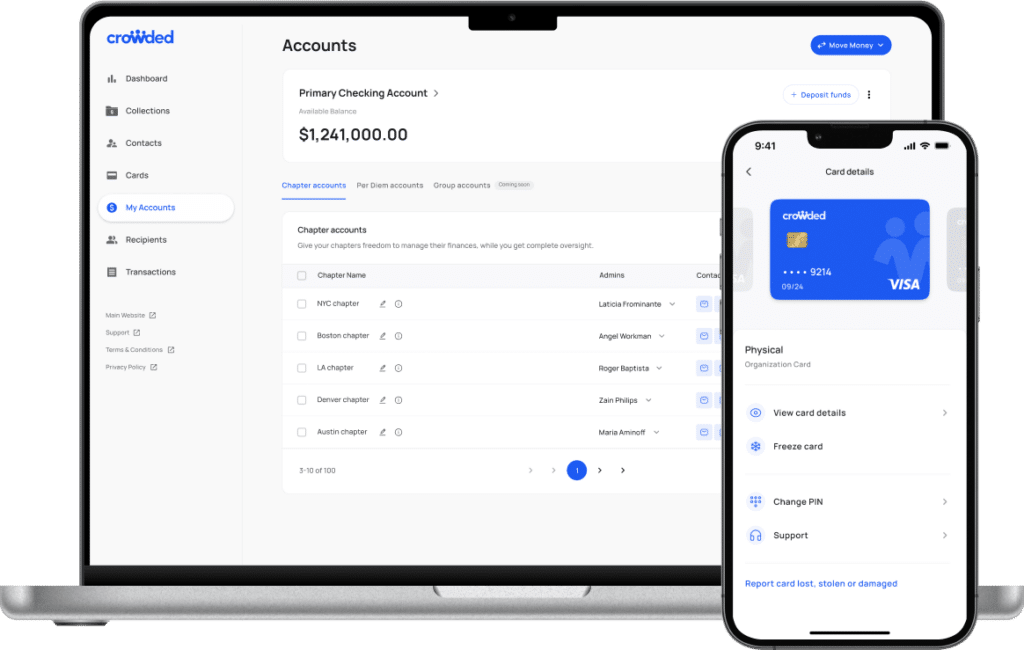
Sub Accounts let nonprofits open separate accounts for its chapters, teams or programs under the organization’s EIN. Chapter leaders manage their own funds, collect payments and spend with Visa® debit cards, while headquarters gets visibility and oversight from one dashboard.*
- Tiered account structure for transparent finances across an organization
- Custom-level restrictions for fully functional Crowded Sub Accounts, with added oversight for the HQ
- One-click payout distribution and allocation
How it works
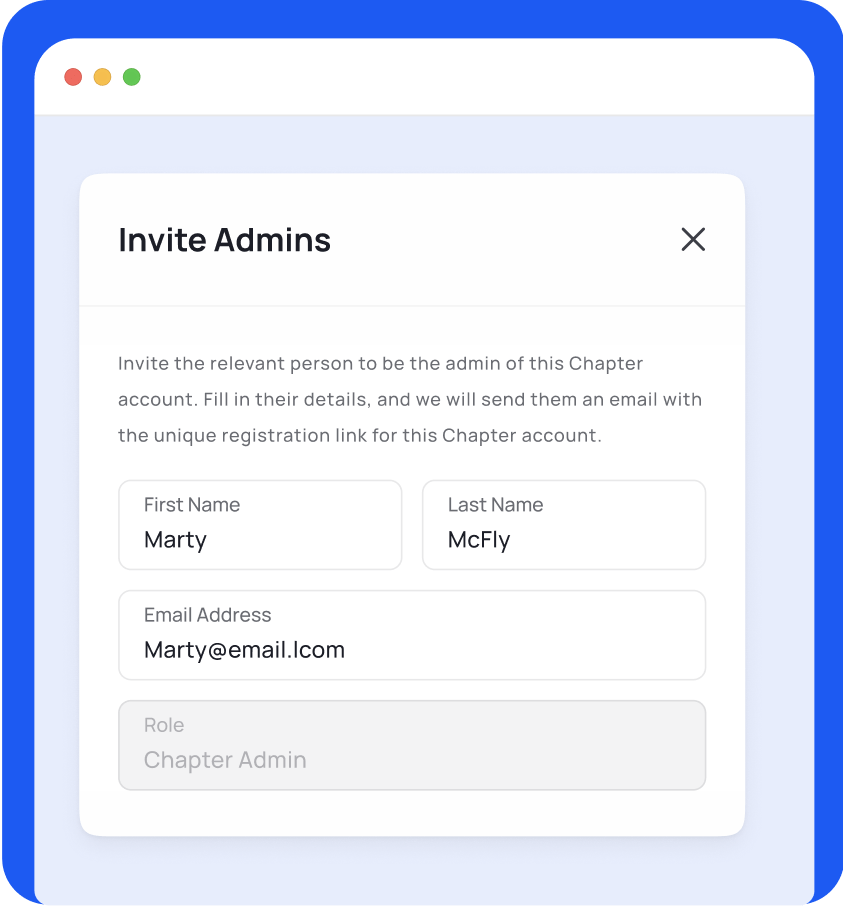
Onboard Leaders as Admins
Much easier than opening a full bank account! No EIN or incorporation documentation required.
Chapters Manage Funds Autonomously
Admins enjoy built-in payment processing and transparent spending tools.
HQ Gets Total Oversight
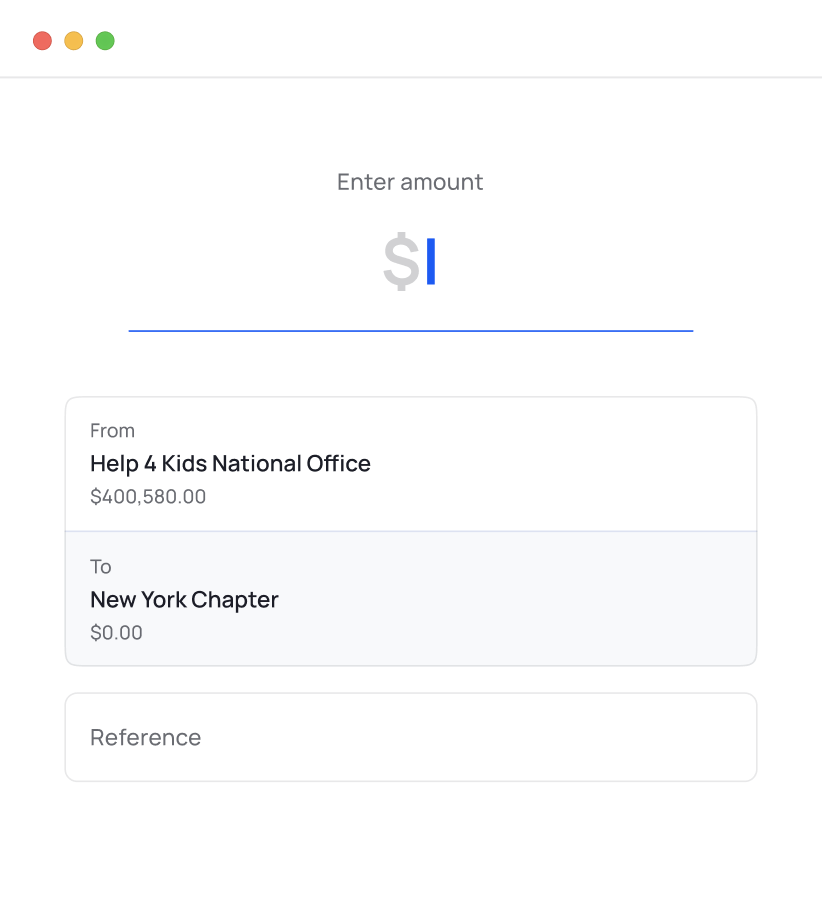
Funds can be added or withdrawn from Sub Accounts, and accounts can be monitored from a central dashboard.
Tiered Banking
Enjoy the efficiency of unified banking* across chapters
- Add and remove funds instantly for free
- Save time with 100% digital accounts (No need to travel to authorize bank accounts or change signatories!)
- Instant account opening with no EIN or incorporation documents required
- Accounts can be frozen to prevent fund mismanagement
transparent sub accounts
Oversee chapters under one account
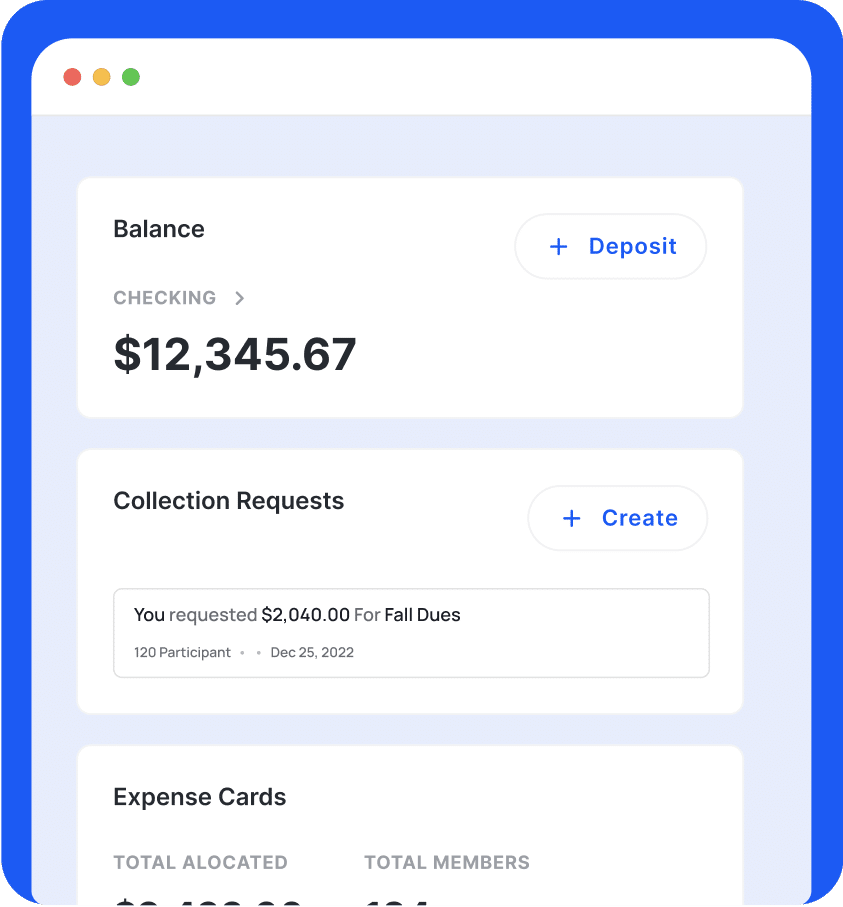
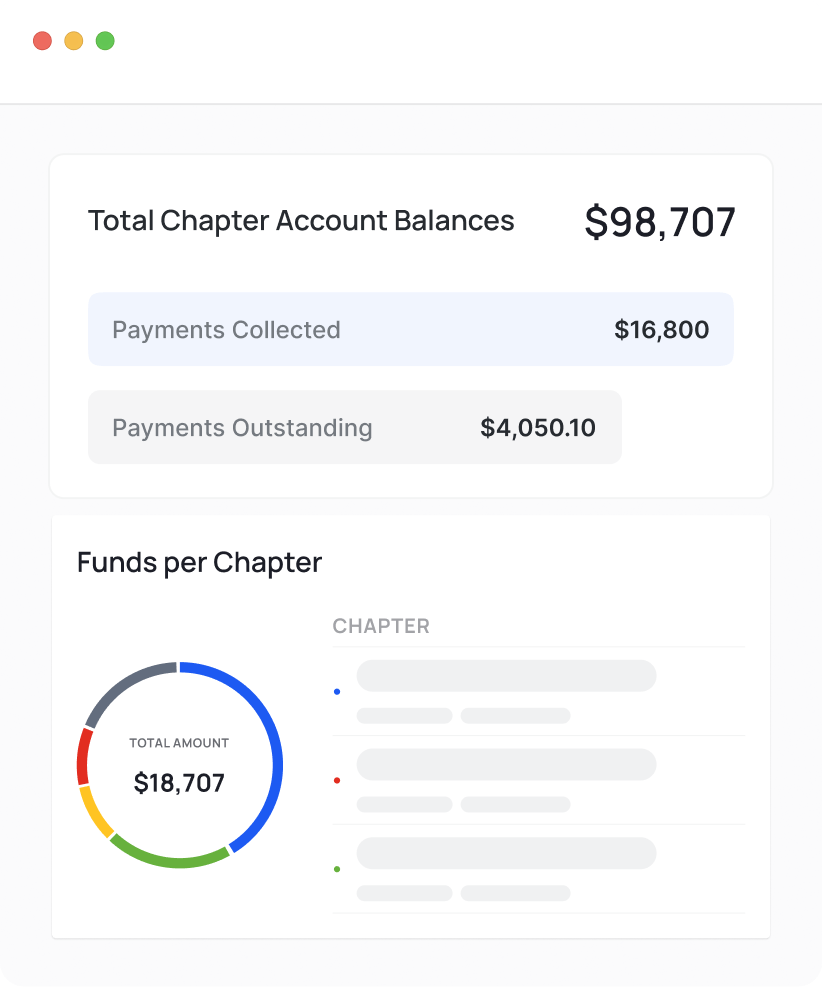
- One clear dashboard with account information & balances
- Add or remove account admins instantly anytime
- Track cash inflows and outflows, deposit or withdraw anytime
- Monitor account finances at the level of insight desired
- Easily identify struggling accounts and step in if necessary
answered.
Want to chat? Contact us.
What is a Sub Account?
A Sub Account is a separate account nested under your organization’s main Crowded account. Each chapter, team or program gets its own balance, transactions and admins, while the organization keeps oversight from one dashboard.
What types of organizations can use Sub Accounts?
Sub Accounts are built for nonprofits whose chapters, teams, or programs operate under the organization’s EIN. Common examples include Girl Scout councils, sports leagues, university departments, certain associations, greek life organizations, large charities, and foundations. If each chapter has its own EIN, learn more about our Related Entities Tracker.
How much does it cost to use Sub Accounts?
Two Sub Accounts are included in the Pro plan, or purchase as many as your organization needs as Add Ons! Please see our pricing page for the most up-to-date prices. To implement more than a handful of Sub Accounts, get in touch with us for a personalized quote for your organization.
What do chapter leaders need to get started?
Chapter leaders verify their phone number, email and date of birth, and can then start managing their Sub Account right away. They don’t need to provide an EIN, incorporation documents, an SSN or a driver’s license.
Once they fill out their information, they can immediately start managing their Sub Account – creating payment collection links, spending funds with Crowded cards, and all other financial transactions.
Do Sub Accounts need to have an EIN?
Sub Accounts are specifically for organizations whose subsidiary groups do not have their own EIN, and are nestled under a central organization. Sub Accounts do not need to provide any of the documentation that is normally required for opening a bank account: EIN, Incorporation documents, SSN or driver’s license.
What visibility do Sub Account admins have?
Sub Account admins see only their own Sub Account: its balance, transactions and collection history. They can’t see the HQ account or any other Sub Account unless they’re invited to it.
Can HQ move money between Sub Accounts?
Yes. HQ admins can add funds to any Sub Account from the organization’s main account in a few clicks, and can withdraw funds back to the main account. Transfers between your own accounts post right away, and HQ can freeze a Sub Account if funds need to be protected.
Are Sub Account funds FDIC insured, and is coverage per chapter or per organization?
Yes, funds in Sub Accounts are eligible for FDIC insurance through i3 Bank, Member FDIC**, and coverage is calculated per organization, not per Sub Account. Because Sub Accounts sit under your organization’s EIN, your organization’s combined deposits are eligible for up to $3,000,000 in coverage through i3 Bank’s deposit sweep program, up to $250,000 at each program bank.*
What happens when a chapter leader steps down?
The HQ swaps in the new leader without needing to open a new account or change bank signatories. An HQ admin invites the incoming leader as a Sub Account admin and removes the outgoing one. Each Sub Account always keeps at least one admin, so HQ can add itself to cover any gap.
Do Sub Accounts have their own account and routing numbers?
Each Sub Account has its own unique account number and shares its routing number and account name with the organization’s main account. Members, donors, or partners can send ACH or wire transfers directly to a specific chapter’s Sub Account.
My chapters each have their own EIN. Can we still use Crowded?
Yes, but Sub Accounts aren’t the right fit. If each chapter has its own EIN, each chapter opens its own Crowded account, and HQ can track chapter finances and filing status through the Related Entities Dashboard. Some organizations choose to consolidate chapters under one EIN; see how NPMA did it.
See how other multi-chapter organizations maintain oversight
Financial oversight without the headaches
160+ hours a year saved
17,000 hours a year saved
- Create an account
- Onboard chapters
- Consolidate your financial management

Let’s chat!
Darryl Gecelter
