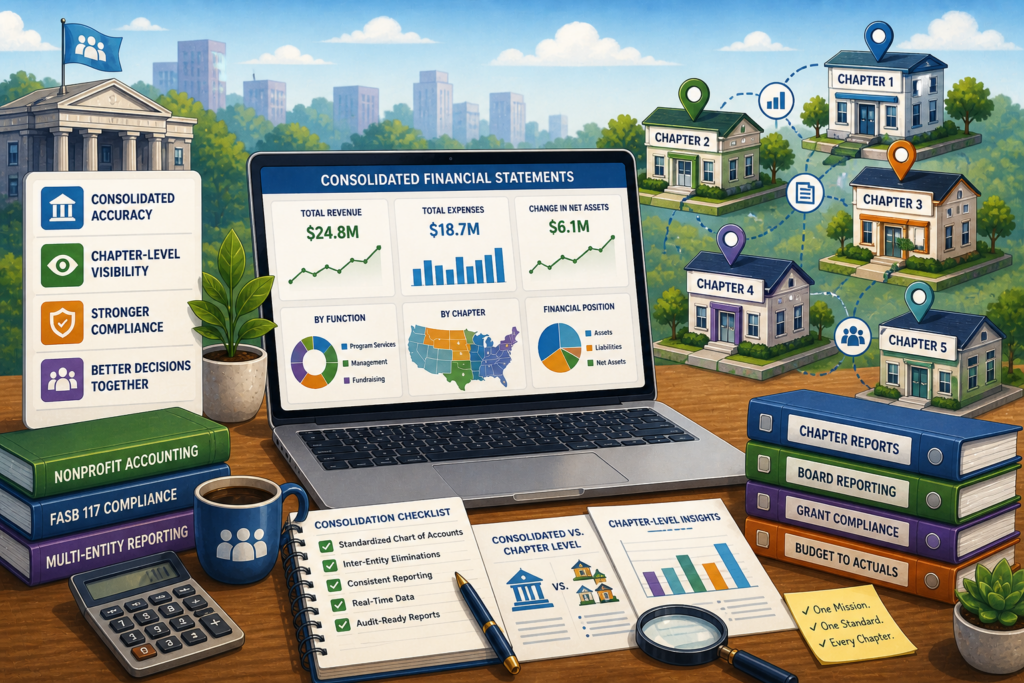
Nonprofit financial statements give leaders a clear view of revenue, expenses, assets, liabilities, cash flow, and net assets. For multi-chapter nonprofits, the challenge is harder: headquarters need consolidated reporting, but local chapters still need visibility into their own activity.
The tradeoff is real. Consolidation helps boards, auditors, lenders, and funders see the organization as one financial entity. But if the process flattens every chapter into a single total, CFOs lose the detail they need to spot risk, support local treasurers, and manage compliance before problems reach year-end. That makes consolidation an infrastructure problem. The goal is to produce statements that preserve chapter-level truth.
TL;DR
- Nonprofit financial statements should show both the full organization and each chapter’s financial reality. Consolidation is useful, but it can hide local risks if chapter-level data disappears.
- Multi-chapter nonprofits need more than year-end reporting. CFOs need clean sub-account data, transfer tracking, restricted fund visibility, and standardized categories throughout the year.
- Consolidation entries make reports cleaner, but they can also erase context. Inter-entity transfers, chapter payables, and local balances must stay traceable after elimination.
- Crowded helps finance teams preserve chapter-level visibility while preparing cleaner consolidated reports. Its infrastructure supports centralized oversight without taking operational control away from local chapters.
- The strongest nonprofit financial statements are built before audit season. With the right systems, finance leaders can catch compliance gaps, cash issues, and reporting inconsistencies before they become board-level problems.
What Are Nonprofit Financial Statements?
Nonprofit financial statements are formal reports that show how an organization receives, uses, holds, and manages financial resources. Unlike for-profit reporting, nonprofit reporting centers on accountability. The question is “How well did we steward restricted and unrestricted resources?”
The four basic nonprofit financial statements are:
- Statement of Financial Position: Assets, liabilities, and net assets.
- Statement of Activities: Revenue, expenses, and changes in net assets.
- Statement of Functional Expenses: Expenses by function and natural category.
- Statement of Cash Flows: Cash coming in and going out.
For a multi-chapter nonprofit, each statement must answer two questions at once: what happened across the whole organization, and what happened at each chapter.
Do Nonprofits Have P&L Statements?
Nonprofits do not typically use a traditional profit and loss statement; the nonprofit equivalent is the statement of activities. A P&L statement shows whether a business generated profit. A nonprofit statement of activities shows whether resources increased or decreased across categories such as contributions, program revenue, grants, events, salaries, occupancy, and program expenses.
The difference matters. A chapter may show a surplus because it received restricted grant funds in March, but those funds may be legally limited to a summer program. Treating that as “profit” can mislead local leaders. For CFOs, the practical takeaway is simple: use business-friendly language when needed, but keep the internal reporting model aligned with nonprofit accounting realities.
How to Consolidate Nonprofit Financial Statements
To consolidate nonprofit financial statements, combine financial activity across the parent organization and chapters, then remove internal activity that should not appear as external revenue or expense.
A basic consolidation process looks like this:
- Collect trial balances from headquarters and all chapters.
- Standardize the chart of accounts.
- Map chapter activity to shared revenue, expense, asset, liability, and net asset categories.
- Identify inter-entity transactions.
- Record consolidation entries.
- Review consolidated and chapter-level reports side by side.
Example: Headquarters transfers $25,000 to Chapter A for a regional program. Chapter A records it as income. Headquarters records it as an expense or transfer. In consolidation, that internal transfer should be eliminated so the organization does not overstate total revenue or expenses. The key is traceability.
What Consolidation Method Should Multi-Chapter Nonprofits Use?
Multi-chapter nonprofits generally consolidate when headquarters have financial control or an economic interest that meets nonprofit consolidation rules. Under nonprofit consolidation ASC 958-810, organizations must assess whether related entities should be consolidated based on control and economic interest. This can apply when a national nonprofit controls local chapters, affiliated foundations, supporting organizations, or related entities.
The practical question is: does headquarters have the power to direct significant financial and operating decisions, and does it have access to benefits or exposure to obligations?
For example, if a national nonprofit controls chapter bank accounts, approves budgets, appoints officers, and requires chapters to follow central financial policies, consolidation may be appropriate. If chapters are legally separate with independent boards and no controlling financial relationship, the analysis may differ.
CFOs should work with auditors on final determinations, but the internal system should still be built to capture clean entity-level data.
What Are the Effects of Consolidation Entries?
Consolidation entries remove internal transactions so the final statements show only activity between the nonprofit group and outside parties.
Common consolidation entries include:
- Eliminating transfers between headquarters and chapters.
- Removing intercompany receivables and payables.
- Adjusting duplicated income or expenses.
- Reclassifying chapter activity into standardized categories.
- Aligning restricted and unrestricted net asset reporting.
Example: Chapter B owes headquarters $10,000 for shared insurance. Headquarters records a receivable. Chapter B records a payable. On the consolidated statement of financial position, both should be eliminated because the organization cannot owe money to itself.
The effect is cleaner external reporting. The risk is losing the local story behind those entries.
How Consolidation Can Disguise Chapter-Level Information
Consolidation can disguise information when chapter activity is merged into totals without preserving local detail. A consolidated statement may show that the organization has strong cash reserves. But one chapter may be carrying excess funds while another is close to missing payroll, vendor payments, or grant deadlines.
This is where multi-chapter reporting can break down. Aggregated totals may hide:
- Chapters with negative cash trends.
- Restricted funds used incorrectly.
- Late reconciliations.
- Local overspending.
- Weak documentation for grants or donations.
- Compliance threshold issues.
Example: Three chapters each raise $42,000, $48,000, and $51,000. At the consolidated level, the total looks routine. At the chapter level, one chapter has crossed an internal review threshold and may need additional documentation, board review, or support before filing season.
Consolidation should never become camouflage.
How Crowded Helps Preserve Visibility While Consolidating
Crowded helps multi-chapter nonprofits manage financial activity at the chapter level while giving headquarters centralized visibility across the organization.
Crowded acts as the infrastructure layer between local chapter operations and centralized finance oversight. Instead of forcing CFOs to reconstruct chapter activity from disconnected bank accounts, spreadsheets, and delayed reports, Crowded keeps financial activity organized closer to where it happens.
For multi-chapter nonprofits, that means:
- Chapter-level sub-accounts can separate local activity without cutting headquarters out of visibility.
- Granular permissions can support local treasurers while keeping central finance controls in place.
- Transaction categorization can make reporting cleaner before month-end or year-end.
- Centralized dashboards can help headquarters monitor chapter balances, activity, and compliance status.
- 990-related workflows can support cleaner filing preparation when financial data is already structured.
The outcome is fewer blind spots. CFOs can consolidate nonprofit financial statements while still seeing which chapter generated the revenue, incurred the expense, received the transfer, or needs follow-up.
Conclusion
Strong nonprofit financial statements do more than satisfy auditors. They help finance leaders see whether the organization is healthy, compliant, and ready to grow.
For multi-chapter nonprofits, consolidation should create clarity. The best reporting model gives headquarters a complete organizational view while preserving the chapter-level visibility needed to manage cash, compliance, restrictions, transfers, and local accountability.
Crowded supports that operating model by helping nonprofits structure financial activity at the source, so consolidation becomes a cleaner process instead of a year-end rescue mission.
Frequently Asked Questions
How often should nonprofits update financial statements?
Most nonprofits should review financial statements monthly, especially multi-chapter organizations. Crowded helps by keeping chapter activity structured throughout the year, so reporting is review-ready instead of cleanup-heavy.
What is the difference between consolidated and combined financial statements?
Consolidated statements merge related entities and remove internal transactions. Combined statements show entities side by side without fully eliminating internal activity.
How do nonprofits track restricted funds across chapters?
Restricted funds should be separated by purpose, chapter, and donor requirements. Crowded helps preserve this detail by organizing transactions at the chapter level before reporting.
What happens if nonprofit financial statements are inaccurate?
Inaccurate statements can delay audits, weaken grant applications, and create compliance risk. For multi-chapter nonprofits, one chapter’s reporting gap can affect the whole organization.
Can nonprofit financial statements be automated?
Parts of reporting can be automated, including categorization, aggregation, and document preparation. Crowded helps automate the groundwork while keeping finance teams in control of final review.