

501(C)(3) Group Exemption: How It Works, Group Exemption Numbers, and Ongoing IRS Compliance
A 501(c)(3) group exemption allows a central nonprofit organization to extend its tax-exempt status to subordinate chapters or affiliates without each entity applying individually to the IRS. For national nonprofits, federated associations, and chapter-based organizations, a group exemption can dramatically reduce administrative burden — but only if it’s structured and maintained correctly.
This guide explains what a 501(C)(3) group exemption is, how the group exemption number works, how it appears on Form 990 and 990-EZ, and what ongoing obligations apply under IRC §6033. We’ll also cover common compliance risks that surface years later, especially when chapter structures evolve.
TL;DR
- A 501(C)(3) group exemption allows subordinate nonprofits to operate under a parent organization’s tax-exempt status.
- Each subordinate typically has its own EIN, but shares a group exemption number tied to the parent.
- The group exemption number appears on Form 990, 990-EZ, and in IRS records.
- Group exemptions reduce application burden, but do not eliminate filing, oversight, or reporting requirements.
- Ongoing compliance is governed by IRC §6033 and related IRS guidance, not just the original approval.
- Most group-exemption problems arise when chapter operations change but oversight systems do not.
- Central visibility into chapter finances and filings is essential to maintaining group exemption status.
What Is a 501(C)(3) Group Exemption?
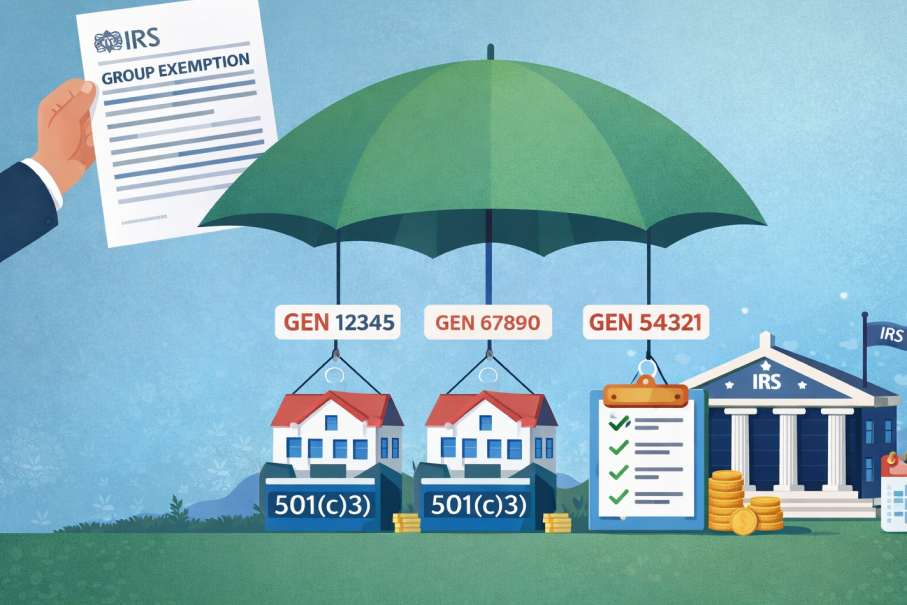
A 501(C)(3) group exemption is an IRS determination that recognizes multiple subordinate organizations as tax-exempt under a single parent organization’s exemption.
Instead of each chapter filing its own Form 1023, the parent organization applies once and certifies that all subordinates meet the IRS requirements for exemption.
What a Group Exemption Does — and Does Not — Do
A group exemption:
- Confers federal tax-exempt status on qualifying subordinates
- Reduces duplicate IRS applications
- Allows centralized recognition under one parent
A group exemption does not:
- Eliminate annual Form 990 filing requirements
- Remove the need for separate EINs in most cases
- Shift compliance responsibility entirely to the IRS
- Automatically keep chapters compliant over time
The IRS expects active, documented oversight by the parent organization.
How the Group Exemption Number Works
When the IRS approves a group exemption, it assigns a group exemption number to the parent organization.
What Is a Group Exemption Number?
The group exemption number is an identifier used by the IRS to link subordinate organizations to the parent’s exemption. It is not a replacement for an EIN.
Each subordinate generally has:
- Its own EIN
- The same group exemption number as other covered subordinates
Where the Group Exemption Number Appears
You’ll see the group exemption number on:
- Form 990
- Form 990-EZ
- IRS determination records
- Public charity lookup tools
This is why searches like “990 group exemption number” and “group exemption number 990 EZ” are common — organizations often need to confirm how chapters should report.
Do Subordinate Organizations Still Need Their Own EIN?
Yes — in almost all cases.
Even under a 501(C)(3) group exemption, each subordinate organization typically:
- Has its own EIN
- Maintains its own bank accounts
- Files its own Form 990 (unless included in a group return)
Sharing EINs between legally distinct organizations is not permitted, even under a group exemption.
IRS Rules Governing Group Exemptions (The Legal Framework)
Group exemptions are governed by a series of IRS rules and revenue procedures that define ongoing responsibilities, not just initial approval.
IRC §6033: Ongoing Filing Obligations
Under IRC §6033, every tax-exempt organization must file an annual information return unless specifically exempt.
For group exemptions, this means:
- Subordinates must file Form 990, 990-EZ, or 990-N, or
- Be properly included in a group return filed by the parent
Failure to meet these requirements can result in automatic revocation, even if the group exemption still technically exists.
IRS Guidance: Rev. Proc. 68-26, Rev. 80-27, and Related Rules
IRS guidance on group exemptions is rooted in:
- Rev. Proc. 68-26
- Rev. Proc. 80-27 (often searched as 80-27 or 80/27)
- Subsequent clarifications and administrative guidance
These rules establish that:
- Subordinates must be organized and operated exclusively for exempt purposes
- The parent must maintain current records of subordinates
- Oversight must be real and demonstrable, not nominal
IRS Letter 947 and Ongoing Communication
Many organizations encounter IRS Letter 947 when dealing with:
- Group exemption confirmations
- Requests for updated subordinate lists
- Filing or compliance clarification
This letter is often triggered when IRS records don’t align with how chapters are actually operating — a common issue in growing organizations.
How Group Exemptions Appear on Form 990 and 990-EZ
Filing Options Under a Group Exemption
Subordinates may:
- File their own Form 990 / 990-EZ, listing the group exemption number
- Be included in a group return filed by the parent organization
The correct approach depends on:
- Legal structure
- Financial independence
- Governance model
- IRS expectations under §6033
Using the wrong approach is a frequent source of compliance errors.
Common Compliance Risks with 501(C)(3) Group Exemptions
Most group exemption issues do not arise at approval. They surface years later.
Where Problems Usually Begin
- Chapters grow financially but remain on 990-N
- Filing responsibility is unclear at the chapter level
- Central oversight increases, but documentation does not
- Subordinates dissolve or go inactive without notice
- EINs remain open after operations stop
These gaps often go unnoticed until:
- An IRS review
- A grantor due diligence request
- A bank compliance check
- A leadership transition
What Parent Organizations Must Monitor Over Time
For HQ leaders, group exemption compliance is an ongoing governance responsibility, not a one-time filing.
Key Areas to Monitor
- Which chapters are active vs inactive
- Which EINs are still open
- Which entities are filing (and which are not)
- Whether chapters qualify for 990-N, 990-EZ, or full 990
- Where financial control actually sits
Without centralized visibility, even well-intentioned organizations accumulate risk quietly.
How Crowded Helps Organizations Manage Group Exemption Compliance
Maintaining a 501(C)(3) group exemption requires more than understanding IRS rules — it requires systems that reflect how organizations actually operate.
Crowded supports group-exempt nonprofits by helping them:
- Track chapter-level financial activity by EIN
- Maintain visibility into filing status across subordinates
- Support accurate Form 990 and 990-EZ preparation
- Preserve financial records through leadership transitions
- Reduce reliance on spreadsheets and institutional memory
Rather than replacing legal advice, Crowded provides the financial clarity and operational structure that makes compliance sustainable over time.
Final Takeaway
A 501(C)(3) group exemption can simplify nonprofit growth — but only when governance, filings, and financial reality stay aligned.
The IRS does not evaluate intent. It evaluates records.
Organizations that treat group exemption compliance as an ongoing process — supported by real visibility into chapters, EINs, and filings — are far better positioned to avoid surprise revocations, audits, and funding disruptions.
Your questions, answered.
Can a nonprofit lose its group exemption?
Yes. A parent organization can lose its group exemption if it fails to meet ongoing IRS oversight and reporting obligations. Common triggers include missing Form 990 filings by subordinate organizations, incomplete or outdated subordinate records, or an inability to demonstrate active oversight under IRC §6033.
Maintaining accurate, centralized visibility into chapter activity and filing status is one of the most effective ways to prevent inadvertent loss.
Do all subordinates need to file Form 990?
Yes. A group exemption does not eliminate annual filing requirements. Each subordinate must either file its own Form 990, 990-EZ, or 990-N, or be properly included in a group return filed by the parent organization.
Organizations that rely on decentralized processes often lose track of which chapters have filed. Platforms like Crowded help HQ teams monitor filing status across all subordinates so missed filings don’t quietly accumulate into revocation risk.
Does a group exemption number replace an EIN?
No. A group exemption number links subordinate organizations to the parent’s tax-exempt status, but it does not replace an EIN. Each subordinate generally retains its own EIN for banking, payroll, and reporting purposes.
Tracking EIN-level activity is critical, especially as chapters grow or change. Tools like Crowded help organizations maintain EIN-level financial separation while preserving organization-wide oversight.
Can subordinates file Form 990-EZ under a group exemption?
Yes, if they independently meet eligibility requirements. The group exemption number must still be reported accurately on Form 990-EZ.
Problems arise when eligibility changes over time and no one notices. Centralized financial and filing visibility through platforms like Crowded makes it easier to identify when a chapter may need to change filing types before compliance issues arise.
What happens if a chapter stops operating?
If a subordinate stops operating, the parent organization should document the change, ensure any required final filings are completed, and determine whether the EIN should be closed. Inactive EINs that continue to miss filings are a common cause of automatic revocation under group exemptions.
Organizations using Crowded can more easily identify inactive chapters by monitoring account activity and filing signals, reducing the chance that dormant entities create compliance exposure.
How do organizations track this at scale?
Most group exemption failures stem from lack of visibility rather than lack of intent. Parent organizations need a reliable way to see:
Which chapters are active
Which EINs exist
Which entities have filed (and which haven’t)
Where financial control actually sits
Rather than relying on spreadsheets or annual check-ins, many organizations use platforms like Crowded to maintain ongoing financial and compliance visibility across chapters, helping prevent small gaps from turning into group-wide exemption risk.